Blue Cross LovePet comprehensive review: limits and co-insurance
An independent 2026 review of Blue Cross LovePet comprehensive insurance, including underwriter, medical sublimits, co-insurance, waits and claims.
Quick verdict
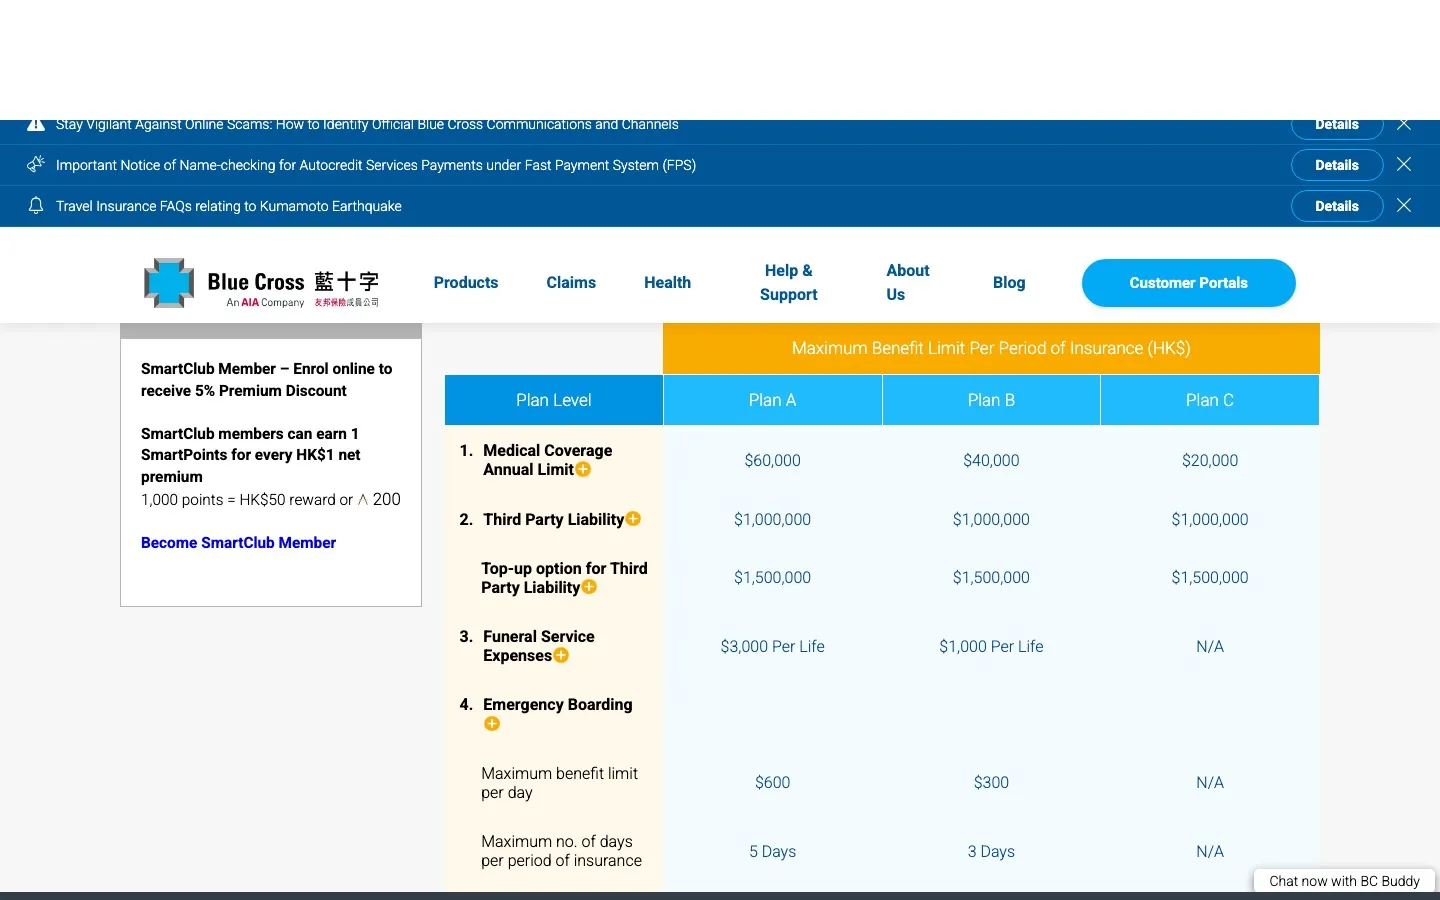
Blue Cross LovePet comprehensive insurance is a conventional, broad package whose real value lies in its schedule—not its HK$20,000/HK$40,000/HK$60,000 annual medical headline. It combines eligible clinical/surgical, consultation/medicine, hospital and chemotherapy benefits with ancillary cover, but category sublimits and age-based co-insurance can materially reduce claims. It is easier to understand than a network product only if you model every line.
DogDogHK reviewed Blue Cross public documents, the Consumer Council’s July 2026 market survey and Insurance Authority information on 11 August 2026; no compensation was received. The issued policy schedule and wording govern cover.
Compare Hong Kong pet insurance.
Product and underwriter
LovePet Insurance is issued by Blue Cross (Asia-Pacific) Insurance Limited. Verify the legal entity against the IA Register of Authorized Insurers and on your proposal/policy. Do not confuse this comprehensive product with the separate LovePet Outpatient product, which has a narrower low-limit design.
The official schedule labels Plan A, B and C with annual medical maxima of HK$60,000, HK$40,000 and HK$20,000 respectively. Covered categories shown include clinical and surgical expenses, room and board, veterinary consultation/prescribed medication and chemotherapy, each subject to its own limits and policy definitions.
Co-insurance, limits and a worked model
Published co-insurance is 30% for attained ages 0–8 and 40% from age 9. Co-insurance is the policyholder’s share of eligible expenses, not the insurer’s. Ageing into the higher band can increase out-of-pocket cost even if treatment and benefit table are otherwise unchanged.
Suppose an age-seven dog has a HK$10,000 bill and HK$8,000 falls within eligible categories and remaining sublimits. At 30% co-insurance, the arithmetic starting point is insurer HK$5,600 and owner HK$4,400 (HK$2,000 ineligible plus HK$2,400 co-insurance). If a smaller consultation, room or category cap applies, payment can be lower. Never apply 70% to the gross invoice without checking sublimits first.
The comprehensive schedule also publishes third-party liability up to HK$1 million with a HK$3,000 excess per claim, plus selected funeral, emergency boarding and overseas benefits by plan. Liability is for defined legal liability, not every complaint involving a dog. Notify the insurer before admitting liability or privately settling.
Waiting periods and exclusions
The official schedule states waits of 7 days for bodily injury, 30 days for other conditions, and 90 days for cancer or chronic renal disease. Symptoms or conditions before commencement or during an applicable wait can interact with the pre-existing-condition definition. Passing day 30 or 90 does not make prior disease covered.
Read the exclusions for preventive/elective care, pre-existing and other defined conditions. Vaccines, parasite prevention, routine grooming/desexing and routine dental care should not be assumed covered. Overseas ancillary cover does not replace immigration, quarantine or overseas-vet documentation rules.
Claims and appointments
Unless your policy and clinic explicitly establish direct settlement, plan to pay the veterinarian and claim reimbursement. Before non-urgent expensive treatment, ask Blue Cross about prior notification or required forms. Do not delay emergency stabilisation for paperwork.
Submit the claim form, itemised invoice, receipt, clinical notes, test reports, prescription and any referral within the current deadline. Ask the vet to allocate each invoice line clearly; this matters because LovePet uses category sublimits. Keep the original and a digital copy.
At application, disclose complete history and answer eligibility questions literally. Do not rely on an intermediary’s verbal assurance that an old symptom “doesn’t count”. Ask for that view in writing and compare it with the wording.
Model repeated treatment, not only one bill
Create a second worksheet for five visits in one year. Apply any per-visit consultation/medicine cap separately, then total the remaining annual category benefit and medical maximum. Repeat at the age-nine co-insurance rate. This exposes products that look adequate for one operation but contribute much less to recurring consultations, or vice versa. Add the annual premium to the owner’s claim share: reimbursement alone is not the complete household cost.
Strengths
- Conventional benefit schedule with three medical annual limits.
- Comprehensive design includes medical and ancillary categories.
- No network reimbursement split in the published core mechanic.
- Waiting periods and age-based co-insurance are clearly displayed.
Watch-outs
- Category and per-benefit limits sit inside the annual headline.
- Owner co-insurance rises from 30% to 40% at attained age nine.
- The annual maximum is not one unrestricted pool.
- Renewal premium, eligibility and wording can change.
- LovePet comprehensive and LovePet Outpatient are separate products.
Best for—and who should skip
Best for owners wanting a traditional medical-plus-liability package and who can model sublimits against likely veterinary invoices. Less suitable if the category you most expect to use has a low cap, the older-age owner share is unaffordable, or known disease is the reason for applying. Keep an emergency fund regardless.
Purchase and claim checklist
- Download the current leaflet, wording, benefit table and quote.
- Verify Blue Cross (Asia-Pacific) Insurance Limited on IA’s register.
- Mark every annual, category, per-day and per-visit limit.
- Calculate owner cost at both 30% and 40% co-insurance.
- Record 7/30/90-day waits and pre-existing definition.
- Disclose full veterinary history and retain the application.
- Confirm reimbursement/direct settlement and claim deadline.
- Request written calculations for any reduced or rejected claim.
Regulatory red flags
Reject pressure to omit medical history, “HK$60,000 means any operation is fully covered”, “no excess” that ignores co-insurance, or an unofficial payment page. Underwriter authorisation is necessary but not a product endorsement. Use Blue Cross’s written complaint route first; then check current Insurance Complaints Bureau jurisdiction and IA information.
Editorial verdict
LovePet comprehensive is a credible conventional structure that rewards careful table-reading. Its clarity is the visible schedule; its trap is treating the annual limit as cash available for any bill. Model the most likely category, older-age share and repeated visits before deciding.
FAQ
Does Plan A pay HK$60,000 for one surgery?
Not necessarily. Category limits, co-insurance, exclusions and prior claims can all reduce payment.
Does co-insurance mean Blue Cross pays 30%?
No. The published 30%/40% is the policyholder share of eligible expenses.
Is LovePet Outpatient the same policy?
No. It is a separate, narrower product; review its own schedule and wording.
Are pre-existing conditions covered after the wait?
No. Waiting periods do not erase pre-existing status.