OneDegree Pet CEO Plan review: Hong Kong pet insurance mechanics
An independent 2026 review of OneDegree Pet CEO Plan, including underwriter, reimbursement, network rules, waiting periods, exclusions, claims and fit.
Quick verdict
OneDegree Pet CEO Plan is Hong Kong’s clearest network-led comprehensive pet-medical structure: high advertised annual limits, no medical-benefit sublimits on the current headline proposition, and up to 90% reimbursement at network clinics for eligible pets aged one or above. Its value depends heavily on network use, age, complete disclosure, exclusions and the ability to pay the clinic first. “90%” never means 90% of every invoice.
DogDogHK reviewed OneDegree public product documents, the Consumer Council’s July 2026 comparison and Insurance Authority information on 11 August 2026; no compensation was received. The issued policy wording and schedule govern cover.
Compare Hong Kong pet-insurance structures.
Product and underwriter identity
Pet CEO Plan is underwritten by OneDegree Hong Kong Limited, a Hong Kong virtual insurer. Verify the legal name in the IA Register of Authorized Insurers, then make sure it matches the proposal, policy and payment page. An IA licence establishes authorisation, not value for your dog.
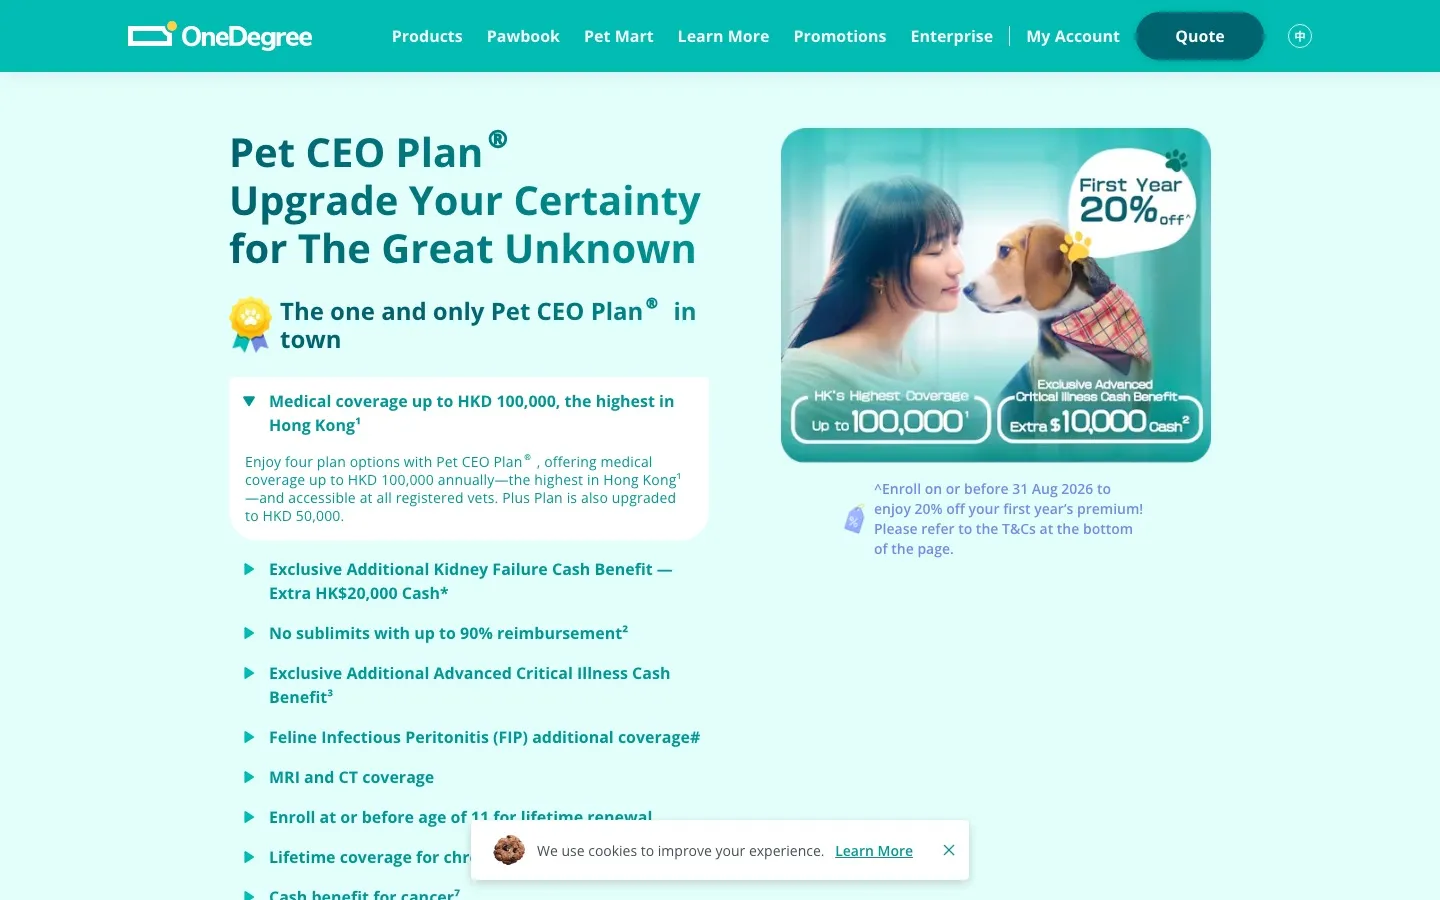
The official page currently advertises tiered annual medical cover up to HK$100,000. Optional riders and promotional discounts can appear; they are not automatically part of the core plan and first-year discounts do not lock the renewal premium.
Reimbursement and network mechanics
For pets aged one or above, the provider advertises up to 90% reimbursement of eligible expenses at network clinics and 70% outside the network. Pets enrolled from 13 weeks to 11 months use a published 50% reimbursement rate at Hong Kong registered vets for that policy year. New enrolment is shown from 13 weeks through 11 years, with no renewal age limit stated, subject to the actual wording and continued renewal.
Network status is not cashless settlement. Unless current documents and clinic confirm direct billing, expect to pay first and claim. Check the clinic on the treatment date. In a genuine emergency, the nearest capable hospital may be outside network, producing a materially larger owner share.
Worked example—not a claim promise
Assume a network bill is HK$20,000. If HK$18,000 is eligible and the applicable reimbursement is 90%, the arithmetic starting point is HK$16,200 insurer / HK$3,800 owner (the HK$2,000 excluded plus 10% of eligible expenses). Annual limits, policy definitions and sums already claimed can reduce payment. Outside network at 70%, the same eligible amount starts at HK$12,600 insurer / HK$7,400 owner. Always calculate from eligible, not invoiced, cost.
Waiting periods and exclusions
The current product page states 28 days for accidents, illnesses and the optional FIP rider, and 180 days for malignant cancer, Prestige MRI/CT and specified optional cash benefits. Read the exact schedule: a symptom or condition first arising before commencement or during a wait may become pre-existing and remain excluded after the wait.
Published exclusions include pre-existing conditions, congenital conditions, oral/periodontal disease, neutering/pregnancy and preventive treatment, subject to full definitions. Do not assume vaccinations, routine dental cleaning, flea control or desexing are medical claims merely because a vet performs them.
OneDegree advertises continued chronic-illness features under conditions, including first insurance at age four or younger. Read the precise clause. It is not a promise that every recurring symptom or pre-existing illness becomes covered indefinitely.
Claims logistics
Before treatment where practical, check network status, prior-authorisation requirements and document deadlines. For emergencies, do not delay necessary care for paperwork. Retain the itemised invoice, receipt, clinical notes, test reports, prescription and referral. Ask the vet to separate consultation, diagnostics, medicine, procedure and boarding.
Disclose full prior history at application: limping, vomiting, skin/ear problems, masses, dental findings, tests and medication can matter even without a formal diagnosis. Never let a seller suggest omitting old symptoms.
OneDegree’s February 2026 FAQ says plans cannot be changed mid-term; changes may be requested before renewal subject to approval, and upgraded benefits can receive new waiting periods and pre-existing restrictions. Treat “upgrade later” as conditional, not guaranteed.
Strengths
- High published annual medical ceiling on upper tier.
- Stronger advertised reimbursement in network.
- No renewal age limit stated, subject to renewal terms.
- Digital-first documents and claims may suit self-directed owners.
Watch-outs
- Network choice changes the owner share substantially.
- Puppy reimbursement is lower during the stated first policy year.
- Waiting-period symptoms can affect later eligibility.
- Renewal premium and terms are not fixed for life.
- Optional riders, promotions and headline limit require separate reading.
Best for—and who should skip
Best for an eligible, currently healthy pet whose owner can use network vets for planned care, fund deposits and keep excellent records. Less suitable if your trusted family/emergency vets are outside network, cash flow cannot absorb the owner share, or an existing condition is the main reason for buying. Insurance cannot retrospectively cover known disease.
This review is not a recommendation for your finances. Compare the premium plus unreimbursed share against a dedicated emergency fund and other current policies.
Purchase and claim checklist
- Download dated wording, benefit table, quote and network list.
- Verify OneDegree Hong Kong Limited on the IA register.
- Obtain and disclose the complete veterinary history.
- Mark waits, exclusions, entry/renewal rules and chronic-condition clause.
- Model one outpatient visit, repeated treatment and a major non-network emergency.
- Confirm whether payment is reimbursement or direct settlement.
- Keep enough cash/credit for clinic deposit and owner share.
- On rejection or reduction, request the calculation and exact clauses in writing.
Regulatory red flags
Avoid unofficial payment links, pressure to hide health history, refusal to provide policy wording, “all bills 90% covered”, “guaranteed cashless” without a clause, or “lifetime” described as a fixed premium. Start disputes through the insurer’s complaint process; check the current jurisdiction of the Insurance Complaints Bureau and IA information channels.
Editorial verdict
Pet CEO Plan is compelling when its network and reimbursement design match real vet use, not simply because HK$100,000 and 90% look large. The responsible comparison is a line-by-line claim model using your likely clinics, age, history and current wording.
FAQ
Does OneDegree pay the vet directly?
Do not assume so. A network reimbursement rate is not the same as cashless settlement; confirm with both insurer and clinic.
Are pre-existing conditions covered after 28 days?
No. A waiting period ending does not turn a pre-existing condition into a covered one.
Can I upgrade later?
The official FAQ says not mid-term; renewal changes require approval and may introduce new waits/re-underwriting.
Is the 90% rate available at every vet?
No. It is the advertised network rate for eligible pets aged one or above; non-network reimbursement is lower and all claims remain subject to terms.